
6G and Satellite Large-Scale Networking: Pragmatic Signals from MWC Shanghai

Recently, MWC Shanghai 2026 kicked off as scheduled. Unlike the lively atmosphere of last year's 5G-A commercial order deluge, this year's exhibition hall was pervaded by a cautious pragmatic sentiment. The '6G Ecosystem Zone' and the 'Future Constellation' satellite area, both set up for the first time, attracted strong interest, but the industry was more keen on discussing 'when will technology turn into real money.'
Our tour found that in the 6G direction, the three major paths of integrated sensing and communication, AI-native, and space-air-ground integration are no longer controversial. Chip makers have even started early pre-research stocking. In the satellite internet field, the 'land grab' for orbital frequencies is basically over, with large-scale networking and cost reduction becoming the new theme.
However, consensus stops at the technology level. Terminal manufacturers and investment institutions are generally staying on the sidelines: the former are waiting for killer applications, the latter can't calculate the return cycle. Even international satellite players that have achieved profitability are struggling in the early cultivation of civilian markets.
When the financial accounts of 5G investments have not yet been fully settled, 6G and satellite internet are collectively entering a transition period of 'clear vision, hard realization.' Technology paths are narrowing, while commercial outlets seem to be widening. Under real investment return constraints, the industry needs a more pragmatic answer than 'grand narratives.'
6G Technology Paths Converge: System Verification Enters Critical Stage

Entering the 6G Ecosystem Zone in Hall N3 of MWC Shanghai, five major sections include the Beijing 6G Lab General Area, Communication Enhancement, Integrated Sensing and Communication, Integrated Communication-Computing-Intelligence, and Space-Terrestrial Integration, breaking down the core technological visions of 6G clearly. On-site staff explained that this is the first time MWC Shanghai has set up a dedicated hall for 6G, sending a clear industry signal that 6G has moved from concept discussion to a critical stage of system verification.
'If last year everyone was still debating what 6G should do, this year the debate is about how to do it and what trade-offs to make,' said a technician in the Beijing 6G Lab General Area. Currently, the three major enhancement paths—integrated sensing and communication, AI-native, and space-air-ground integration—have formed industry consensus. Key technologies such as terahertz communication and intelligent reflective surfaces are also entering prototype verification stages.
The pace of upstream layout in the industry chain is accelerating. At the show, Qualcomm demonstrated an end-to-end 6G prototype system. GalaxySpace publicly displayed its self-developed second-generation phased array antenna for direct-to-device satellite connectivity for the first time in the 6G ecosystem zone. vivo exhibited 6G pre-research prototypes and technology roadmaps. vivo's display direction leans more toward end-to-end systems and application implementation, showcasing a complete 6G trial system including MR terminals, 6G terminal prototypes (UE), 6G base stations (RAN), and core network full-chain components.

A representative from a domestic chip maker said that the company's internal 6G pre-research team size has doubled from last year, with clear logic: 'Starting only after standards freeze is too late; we must build technology reserves ahead of time.'
Terminal manufacturers remain cautious. Responses from several mobile phone brands regarding 6G terminal plans were mostly 'monitoring closely,' and few consumer-grade product demonstrations for 6G were seen on the floor. The 6G pre-research director of a top-five global smartphone maker said in informal discussion that it is currently difficult to provide a clear 6G phone commercial roadmap. The core reason is not insufficient technical capability, but the terminal side's judgment on the transformation path of user needs and application scenarios is still ongoing. They believe that the experience dividends of 5G have not been fully released, and the immersive holographic, multi-sensory scenes envisioned for 6G are still some distance from the mass consumer market.
Investment circles also remain cautious. After watching the 6G zone demonstrations, an early-stage investor commented that the direction of technology evolution is impressive, but from an investment perspective, the capital returns of 5G are still in a digestion cycle. The R&D and network deployment investment scale for 6G is huge, with insufficient data to support exit cycles and return expectations. He admitted that at this stage, he is mainly keeping watch and waiting for clearer commercial signals before acting.
'Future Constellation': Scale Deployment and Cost Control as Main Themes

Unlike the 6G zone's focus on key technology verification, the first-time 'Future Constellation' satellite industry area presents a different industrial rhythm. The orbital landscape is taking shape, and participants are entering a phase of intensive resource and cost management.
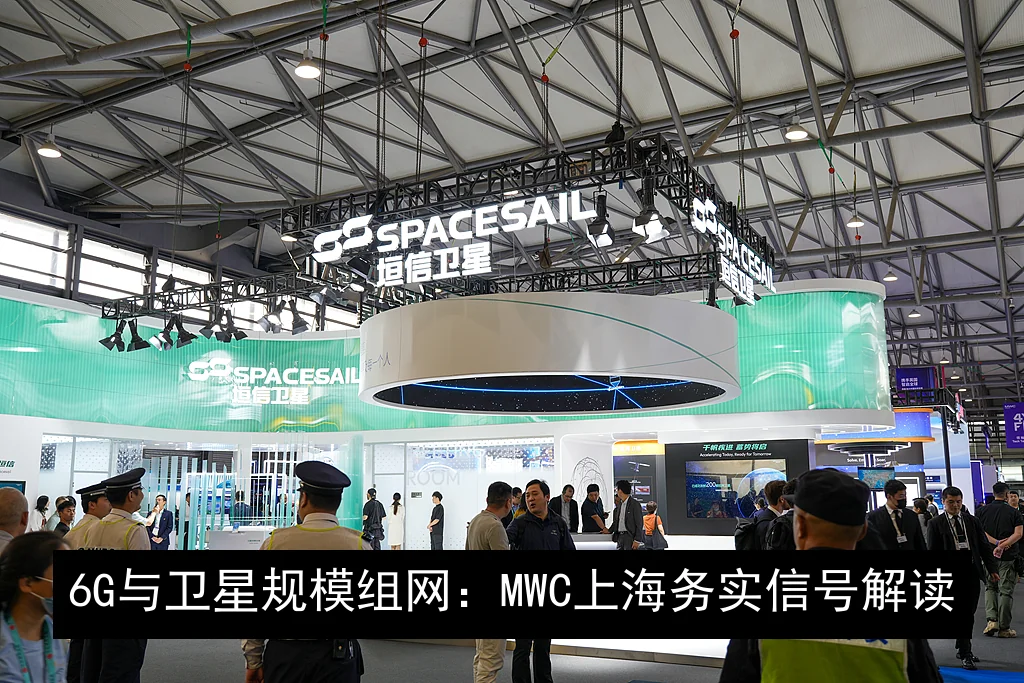
Domestic low-orbit broadband and narrowband constellation operators set up booths alongside international players. Spacety demonstrated real low-orbit satellite internet terminal equipment for scenarios like ocean-going vessels and desert mining areas. Guodian Gaoke showcased the Tianqi constellation's IoT deployment cases. Yuanxin Satellite engineers conducted a live video call test using the 'Qianfan Constellation.'
A representative from Guodian Gaoke said: 'The scramble for satellite internet orbital and frequency resources has basically concluded. The current focus is on scale deployment and cost control.' He revealed that batch production costs for narrowband communication payloads are continuously declining, but the user scale for satellite internet services has yet to reach breakeven. Government and industry orders will remain the revenue base for at least the next few years.
During the formation of profit models, terminal costs are noteworthy. When discussing satellite communication terminal material costs at antenna and module maker booths, interviewees generally said that costs are rapidly decreasing and already capable of being integrated into mainstream handset designs. However, most declined to reveal specific figures.
A business manager at the Iridium booth said that Iridium has achieved positive cash flow relying on narrowband voice and low-speed data services, but traditional market space is nearing saturation. Next growth needs to expand into IoT and emergency communications. Meanwhile, domestic low-orbit broadband constellations are still in a scale-priority catch-up phase, and achieving breakeven will require time and user accumulation.


